

EasyBudget - Budget planning
by Wallet Passes Alliance
4.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.0
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
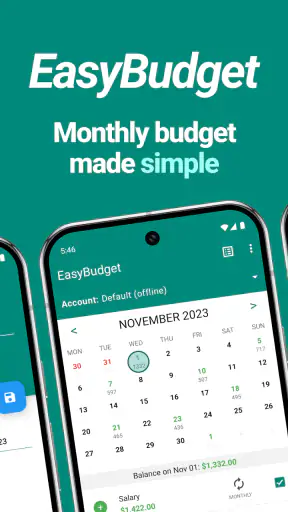
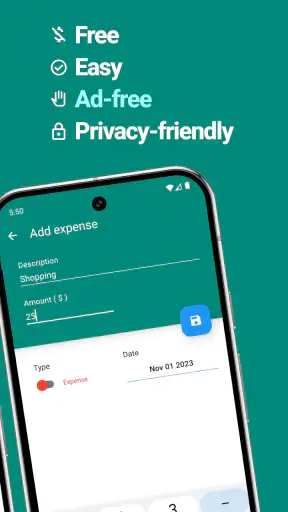
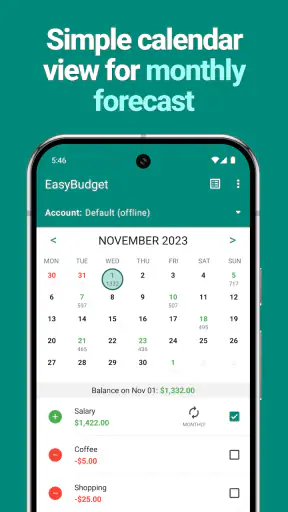
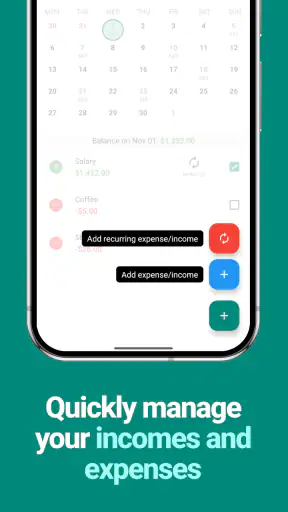
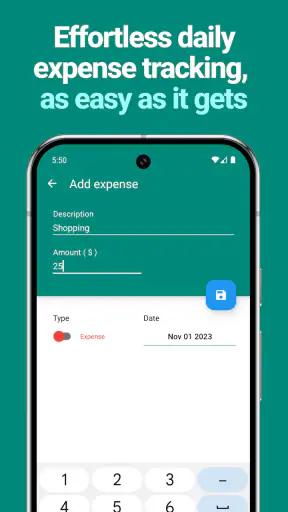
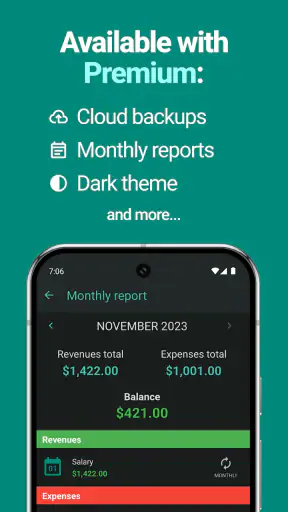
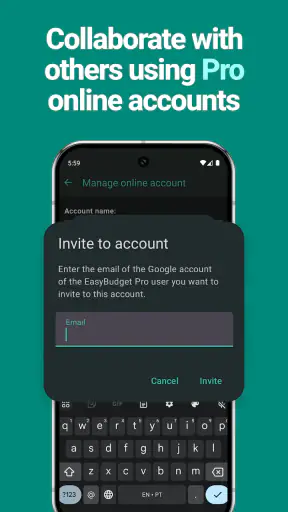
 Analysis by Getfullapps
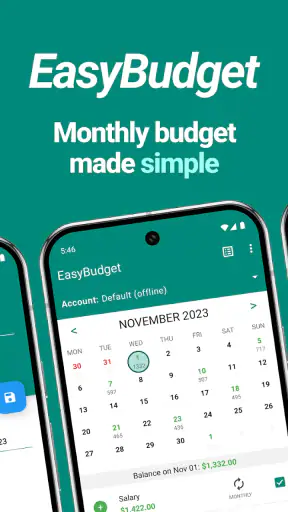
EasyBudget is the kind of finance app I would suggest to someone who wants a clearer month without turning budgeting into a second job. Its central idea is simple: give your monthly money a structure that is easy to read and easy to maintain. That focus matters because many finance tools become crowded with charts, accounts, categories, and financial terminology before a new user has even built a useful habit.
After spending time with it, I see the main value in its direct approach to monthly budget planning. Rather than asking you to become an accountant, it encourages you to decide what money is available, what needs to be covered, and what can safely be spent. That makes it especially approachable for people who currently rely on mental calculations, notes, or a rough balance in their banking app.
Developed by Wallet Passes Alliance, EasyBudget is a free finance app with an Everyone content rating. It has been available since December 2, 2015, and its current version is 4.1.0. The app has reached over 500 thousand installs, with a 4.0 average from around 21 thousand ratings, so it has clearly found an audience among people looking for a straightforward budgeting tool.
Why the monthly budget is the real feature
The most important thing about EasyBudget is not a flashy dashboard or a long list of financial tools. It is the decision to make the month the main unit of planning. I find that useful because most everyday money questions are monthly questions: Can I afford this before payday? How much should remain for groceries? Is there enough room for an unexpected bill?
When a budgeting app tries to cover every possible financial need, the user can lose sight of those practical decisions. EasyBudget keeps attention on the amount you can work with during the current month. That creates a smaller mental task. You are not required to understand your entire financial life before making a useful plan for the next few weeks.
This also changes how I think about spending. A bank balance tells me what is in an account, but it does not always tell me what is already committed. A monthly budget gives that balance context. Money reserved for rent, transport, food, or a recurring payment should not feel available simply because it is still sitting in the account. EasyBudget is most helpful when used to separate available spending from money that already has a job.
The practical strength is clarity before speed. The app does not need to predict every future expense to help with a decision today. It gives a user a place to set the month’s boundaries and then check whether a purchase fits inside them. For someone who tends to overspend in the first half of the month, that simple visual reminder can be more useful than a sophisticated report viewed only once in a while.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Turning a vague intention into a usable plan
I would begin by treating the app as a planning surface, not as a complete replacement for a bank account. Start with the money you expect to have available, then account for the expenses that are difficult to avoid. The important step is to enter those commitments before deciding what is free to spend. If you begin with optional purchases, the budget can look healthier than it really is.
A good first pass does not need to be perfect. I would rather create a realistic plan with a few broad spending areas than spend an hour trying to divide every purchase into an overly precise category. The point is to make the remaining amount meaningful. If the categories are too detailed to maintain, the plan will become outdated and stop helping.
One useful habit is to update the budget at the same time each week. I would check what has already been spent, compare it with the amount still available, and adjust my choices for the days ahead. This is more effective than waiting until the end of the month, when the information may only confirm that the damage has already been done.
Another practical tip is to leave room for irregular expenses instead of assigning every last unit of money to routine categories. A small cushion makes the plan less fragile. Without one, a minor repair, school cost, or unplanned trip can make the entire month appear to have failed. A budget should help you respond to real life, not punish you for having it.
What using it feels like in an ordinary month
Imagine receiving your income near the start of the month. Before making discretionary purchases, you open EasyBudget and map out the obligations that must be handled first. You then set aside amounts for everyday needs and look at what remains. Later, while standing in a shop, you can ask a more useful question than “Is there money in my account?” You can ask, “Does this purchase fit the amount I planned for this part of the month?”
That distinction is small but powerful. A person with a healthy bank balance can still be short later if several payments are due soon. Conversely, someone who sees a modest remaining amount may feel more confident spending it if the important commitments are already covered. The app’s value comes from making that reasoning visible instead of leaving it to memory.
For a household, I would use a shared routine even if only one person maintains the app. At the beginning of the month, agree on the major commitments and the flexible areas. During the month, discuss changes when they happen rather than quietly ignoring the original plan. EasyBudget can support that conversation because the budget becomes a common reference point instead of one person’s private guesswork.
For a student or someone starting their first independent budget, I would keep the plan intentionally broad. Housing, food, travel, bills, and personal spending may be enough at first. The benefit is not a perfect financial record; it is learning how quickly flexible money disappears when several small purchases are treated as harmless on their own.
Where the app is stronger than familiar alternatives
The usual alternative is often a notes app, a spreadsheet, or the budgeting tools built into a banking application. Notes are quick, but they usually leave the user to calculate the remaining amount manually. Spreadsheets can be more powerful, but they ask for more setup and maintenance. Bank apps are excellent for viewing transactions, yet they may focus on what has already happened rather than what you intend to do next.
EasyBudget sits between those choices. It is more purposeful than a loose note and less demanding than a custom spreadsheet. That middle ground is its best argument. I would choose it when I want a dedicated place for a monthly plan but do not want to build formulas, import data, or learn a complex financial system.
Its simplicity also makes it easier to recommend to a family member who avoids budgeting apps because they seem intimidating. A person does not need to be interested in investing, debt analysis, or long-term financial modelling to benefit from a clearer month. The app is aimed at the everyday decision of allocating money, and that narrow purpose can be an advantage.
There is a trade-off, though. Users who want automatic transaction syncing, detailed account reconciliation, investment tracking, or advanced reports may prefer a more comprehensive personal finance platform. EasyBudget’s appeal depends on wanting a focused planner. If you expect the app to explain every movement in every account, its simpler approach may feel limited rather than refreshing.
Small workflows that make the plan more reliable
The first workflow I recommend is a “commitments first” check. Before considering entertainment or shopping, identify expenses whose timing could cause trouble if forgotten. This prevents the common mistake of treating the full account balance as disposable. It also makes the remaining budget more honest, which improves every later decision.
The second is a mid-month reset. Do not wait for the calendar to turn if your circumstances change. If a bill is higher than expected, reduce a flexible area immediately rather than pretending the original plan still works. The app is more useful when it reflects the current situation, not when it preserves an outdated target for the sake of consistency.
The third is to use broad categories as signals rather than moral judgments. If food spending rises, the useful question is what caused it: a busy schedule, higher prices, guests, or repeated convenience purchases. A budget should reveal patterns that help you choose differently next time. It should not turn every overage into a reason to abandon the whole system.
I also find it helpful to separate predictable irregular costs from genuine surprises. Annual renewals, seasonal travel, gifts, and school expenses may not occur every month, but they are not truly unexpected if they happen regularly. Planning for them gradually makes the monthly figure more realistic. This is one area where a simple app requires more thought from the user, but that thought is valuable because it builds awareness rather than hiding the cost.
The friction points worth understanding
EasyBudget’s focused design can become a weakness for people who want automation. A manual budget depends on the user keeping it current. If you forget to record changes or continue spending without checking the plan, the app cannot rescue the month by itself. I see this as the main trade-off: less complexity at the beginning, but more personal responsibility during the month.
There is also a difference between planning and recording. A plan tells you what should happen; a transaction history tells you what did happen. Someone who wants a searchable archive of every purchase may find a dedicated expense tracker or bank integration more suitable. EasyBudget works best when the central question is allocation, not forensic review.
The app is free to download and use, while in-app purchases range from $0.99 to $99.99 per item. That makes it sensible to inspect any optional purchase carefully and decide whether the added value matches the way you budget. A person who only needs a basic monthly structure may not need to spend anything, while a committed user should evaluate upgrades based on actual workflow improvements rather than impulse.
Compatibility is another practical consideration. The listed minimum operating system is Android 7.0, so users on older devices should check their system before planning around it. For supported Android phones, the app’s mature release history is reassuring, but I would still keep a backup of important budget notes if the monthly plan is central to your household decisions.
The 4.0 average suggests a generally positive reception, but I would not treat that number as a guarantee that the interface will suit everyone. Budgeting is personal. Some people want a calm, minimal tool; others want automation, charts, bank connections, and detailed history. The right choice depends less on the rating and more on whether you will actually maintain the kind of plan the app encourages.
Who will benefit most from this approach
I think EasyBudget is a strong fit for a first-time budgeter, someone trying to control discretionary spending, or a user who has outgrown a handwritten monthly list. It is also useful for people paid on a regular schedule who want to divide their available money before spending begins. The app’s focused nature keeps the first step manageable.
It can be particularly helpful during a transition: moving out, starting work, managing a household, or trying to stop reaching the end of the month with no clear explanation. In those situations, the immediate need is often not advanced analysis. It is a dependable way to see what must be covered and what can wait.
I would be more cautious about recommending it to someone with several bank accounts, complicated shared finances, frequent currency changes, or a strong need for automatic categorization. Those users may save time with a broader finance service that connects transactions and produces reports without as much manual upkeep. EasyBudget is not the best answer simply because it is easy; ease matters only when the simpler workflow matches the problem.
It is also not ideal for someone who dislikes checking a budget during the month. A plan created once and ignored will not change spending behaviour. The app can make the numbers easier to understand, but it cannot supply the habit of looking before buying. I would recommend pairing it with a weekly review, even if that review lasts only a few minutes.
My recommendation after using the monthly method
EasyBudget succeeds because it concentrates on a decision most people make repeatedly: how much of this month’s money is genuinely available. Its developer, Wallet Passes Alliance, has kept the product positioned as a practical finance tool rather than an all-purpose financial command centre. That restraint makes it approachable, although it also means users seeking deep automation may eventually want something more advanced.
For me, the strongest result is the change from reactive checking to deliberate planning. Instead of opening a banking app after spending and wondering what happened, I can set boundaries before the month gets busy. That does not eliminate unexpected costs, but it makes them easier to absorb because the rest of the budget has a visible structure.
EasyBudget is free, rated for Everyone, and available in a current 4.1.0 release for devices starting with Android 7.0. Those details make it easy to try without a major commitment. I would begin with one ordinary month, use broad categories, review the plan weekly, and judge the app by whether it helps me make better decisions before spending.
My final view is positive, with one clear condition: choose EasyBudget for a simple monthly planning habit, not for full financial automation. If that is the problem you want to solve, it offers a clear and approachable way to start. If you need connected accounts, detailed transaction analysis, or complex household reporting, a more comprehensive alternative will probably serve you better.
Pros
- Clear overview of income, expenses, and remaining balance
- Simple budgeting tools suitable for beginners
- Helps identify spending patterns and unnecessary costs
- Useful for setting limits across different expense categories
- Lightweight design that is easy to navigate on mobile devices
Cons
- May lack advanced investment and debt-tracking features
- Manual transaction entry can become time-consuming
- Limited customization for complex budgeting methods
- Some features may require a paid upgrade or subscription
- Data backup and synchronization options may be limited
FAQs for EasyBudget - Budget planning
What is EasyBudget - Budget planning used for?
EasyBudget - Budget planning is designed to help you organize personal finances by recording income, tracking expenses, and planning spending in advance. After reviewing the app, its main appeal is the straightforward approach: you can see where your money goes without dealing with overly complicated financial tools. It is suitable for everyday budgeting, household expense monitoring, and users who want a clearer view of their monthly financial habits.
Is EasyBudget - Budget planning suitable for beginners?
Yes, EasyBudget - Budget planning is generally suitable for beginners because its purpose is easy to understand and the budgeting process is presented in a relatively simple way. New users can start by entering their regular income and expenses, then use the resulting overview to compare planned and actual spending. However, users who need advanced investment analysis, tax management, or professional accounting features may find it limited.
Does EasyBudget - Budget planning require an internet connection?
The basic budgeting functions may be available without a constant internet connection, which is useful when you want to record an expense while traveling or in an area with weak reception. Nevertheless, availability can depend on the app version, device, and any synchronization or backup features being used. Before relying on offline access, it is wise to test adding and saving transactions with mobile data and Wi-Fi disabled.
Is my financial information safe in EasyBudget - Budget planning?
Because EasyBudget - Budget planning can contain sensitive information about your income, purchases, and spending habits, privacy should be considered before entering detailed data. Avoid adding bank passwords, card PINs, or other credentials unless the app explicitly supports secure financial connections. Review the app’s current privacy policy, permissions, backup options, and data-handling practices in the official store listing before downloading or synchronizing your information.
Is EasyBudget - Budget planning free to download and use?
EasyBudget - Budget planning may be available as a free download, but the exact features included without payment can vary between Android and iOS versions and may change after updates. Some editions of budgeting apps use advertisements, optional purchases, or premium tools for additional functions. Check the official Google Play or App Store listing for the current price, subscriptions, in-app purchases, and any limitations before installing.

EasyBudget - Budget planning
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support.easybudget@walletpasses.me, visit https://walletpasses.me/easybudget, or review their https://walletpasses.me/easybudget/privacy/.










